By MMJ Immanuel Benedicto Misagga, Emeritus President Villa
Uganda’s commercial banks have come under criticism for favouring established businesses over start-ups, with MMJ Immanuel Benedicto Misagga arguing that restrictive lending requirements are stifling innovation, industrialisation and job creation.
In a strongly worded commentary, Misagga describes the country’s banking system as one that rewards those who already possess wealth while shutting out entrepreneurs seeking to establish their first businesses.
“Banks in Uganda are not banks; they are supermarkets for the rich! They are not planters; they are harvesters!” he writes, challenging financial institutions to reconsider their approach to financing emerging enterprises.
His argument centres on a familiar predicament: an entrepreneur invests personal savings in a warehouse, purchases machinery and develops a promising business idea, only to be denied a loan because the enterprise lacks an established financial record.
According to Misagga, requirements such as two years of audited accounts, substantial collateral and proof that a business is already operational create an almost insurmountable barrier for first-time entrepreneurs.
He questions the logic of demanding an established operating history from businesses that need financing to begin production, describing the practice as “stone-age banking”.
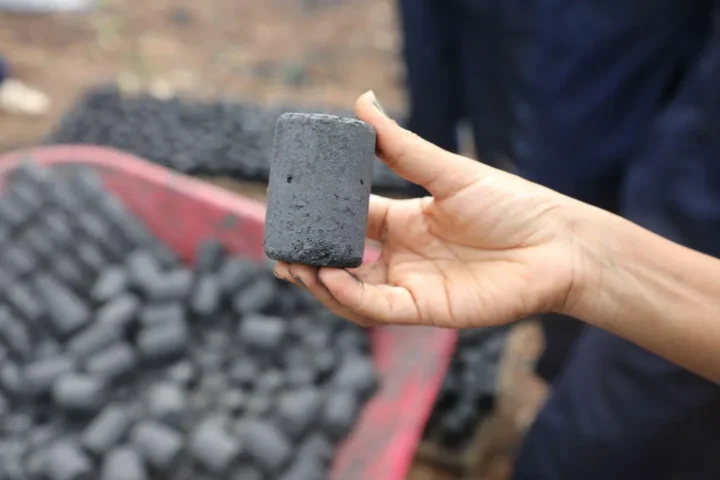
The consequences, he argues, extend beyond individual entrepreneurs to Uganda’s broader economic transformation. Businesses capable of converting waste into charcoal, manufacturing tiles from plastic or processing maize bran into animal feed could create jobs and support environmentally sustainable industrialisation if given access to affordable capital.
Misagga contrasts Uganda’s lending practices with international examples of financing models that have supported industrial development and entrepreneurship, citing Germany’s industrialisation, Japan’s post-war reconstruction and Muhammad Yunus’s pioneering microfinance initiative in Bangladesh.
He also invokes Henry Ford’s automotive revolution to illustrate how investment in innovation and production can transform an idea into an industry.
For Uganda, he argues, the priority should be financing viable business ideas at their earliest stages rather than concentrating credit among established companies and wealthy borrowers.
Misagga consequently calls on the Bank of Uganda to consider stronger measures compelling commercial banks to allocate a defined proportion of their lending to start-ups, green enterprises, youth-led industries and first-time entrepreneurs.
He also urges aspiring business owners to explore alternative financing opportunities, including Emyooga and relevant development and climate-financing programmes.
His proposals raise a fundamental question about the role of commercial banking in a developing economy: should financial institutions concentrate primarily on managing lending risks, or should they also play a more deliberate role in building productive capacity?
While banks must protect depositors’ funds and assess borrowers’ ability to repay, Misagga contends that excessive reliance on conventional collateral and historical financial performance risks excluding promising enterprises before they can demonstrate their commercial potential.
“The Kifuuta Oracle says a nation that only funds what is running will never start what is coming,” he concludes, calling for a financing culture that gives Uganda’s emerging entrepreneurs a realistic opportunity to turn ideas into industries.